

Home insurance premiums have risen by an average of 4% or over $100 nationally in the past year, as the pile-on of rising household expenses continues.
Canstar’s comparison of new policy pricing across more than 40 home insurance providers found the average policy has climbed from $2,319 in 2025 to $2,420 in 2026, almost $50 a week.
The increases are steeper in the Northern Territory and Tasmania, rising by 8% and 6% respectively. The average premium in the NT is now $4,749 a year – the highest of any state or territory. That’s close to $100 per week.
South Australia has the cheapest premiums, with the average home insurance policy costing $1,763.
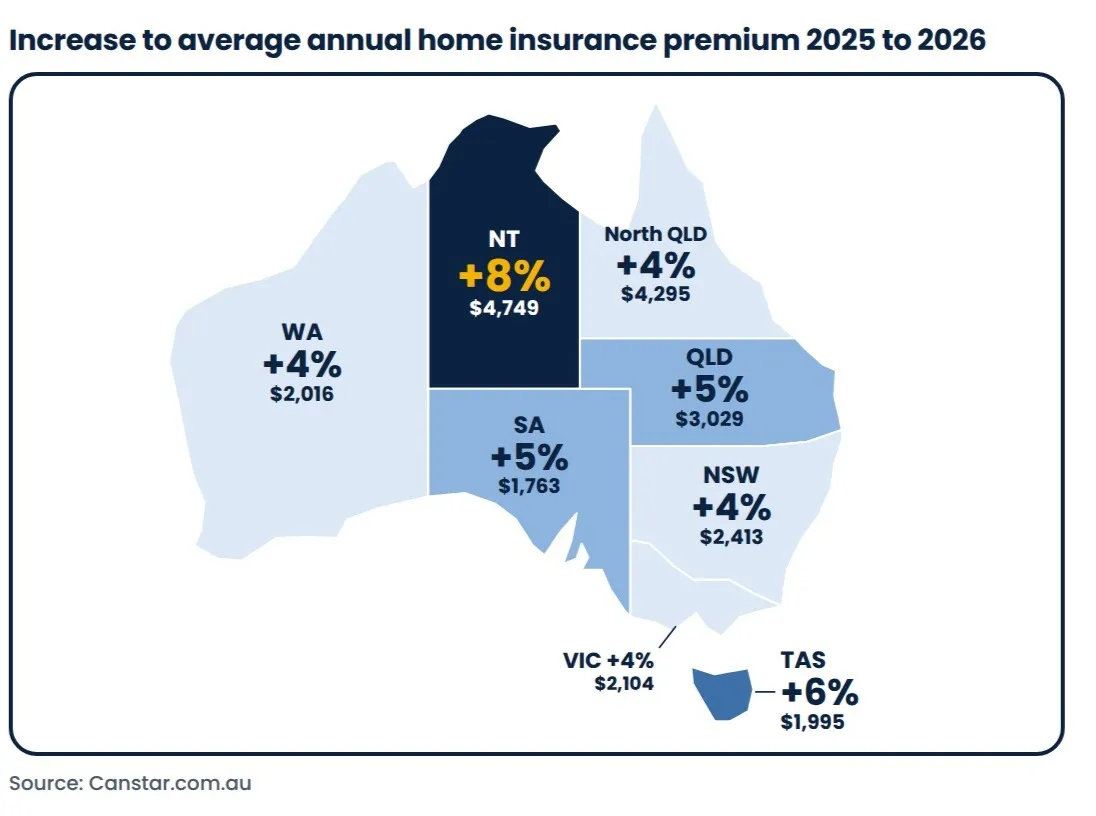
Average home insurance premiums: where costs are rising | |||
|---|---|---|---|
Region | 2025 | 2026 | Change |
NSW | $2,320 | $2,413 | +$93 (+4%) |
VIC | $2,024 | $2,104 | +$80 (+4%) |
North QLD | $4,118 | $4,295 | +$177 (+4%) |
QLD* | $2,882 | $3,029 | +$147 (+5%) |
SA | $1,676 | $1,763 | +$87 (+5%) |
WA | $1,945 | $2,016 | +$71 (+4%) |
TAS | $1,883 | $1,995 | +$112 (+6%) |
NT | $4,394 | $4,749 | +$355 (+8%) |
National | $2,319 | $2,420 | +$101 (+4%) |
Source: Canstar. Premiums based on quotes obtained for Canstar's 2025 & 2026 Home Insurance Awards, for a range of addresses, property assumptions and building sum insured amounts. National average based on state averages weighted by state population per ABS national, state and territory population (March 2026). *QLD excludes the portion of the state north of, but not including, Rockhampton.
The extent of any increase over the past 12 months will depend on the property, location, level of cover and insurer. Existing customers may see different premium changes than new customers.
What’s pushing premiums to rise?
More frequent extreme weather events, rising construction costs and higher administrative expenses are all putting pressure on home insurance premiums.
Cotality’s Cordell Construction Cost Index shows building costs have accelerated once again, with a 1% increase in the September quarter, resulting in an annual rise of 3.2%.
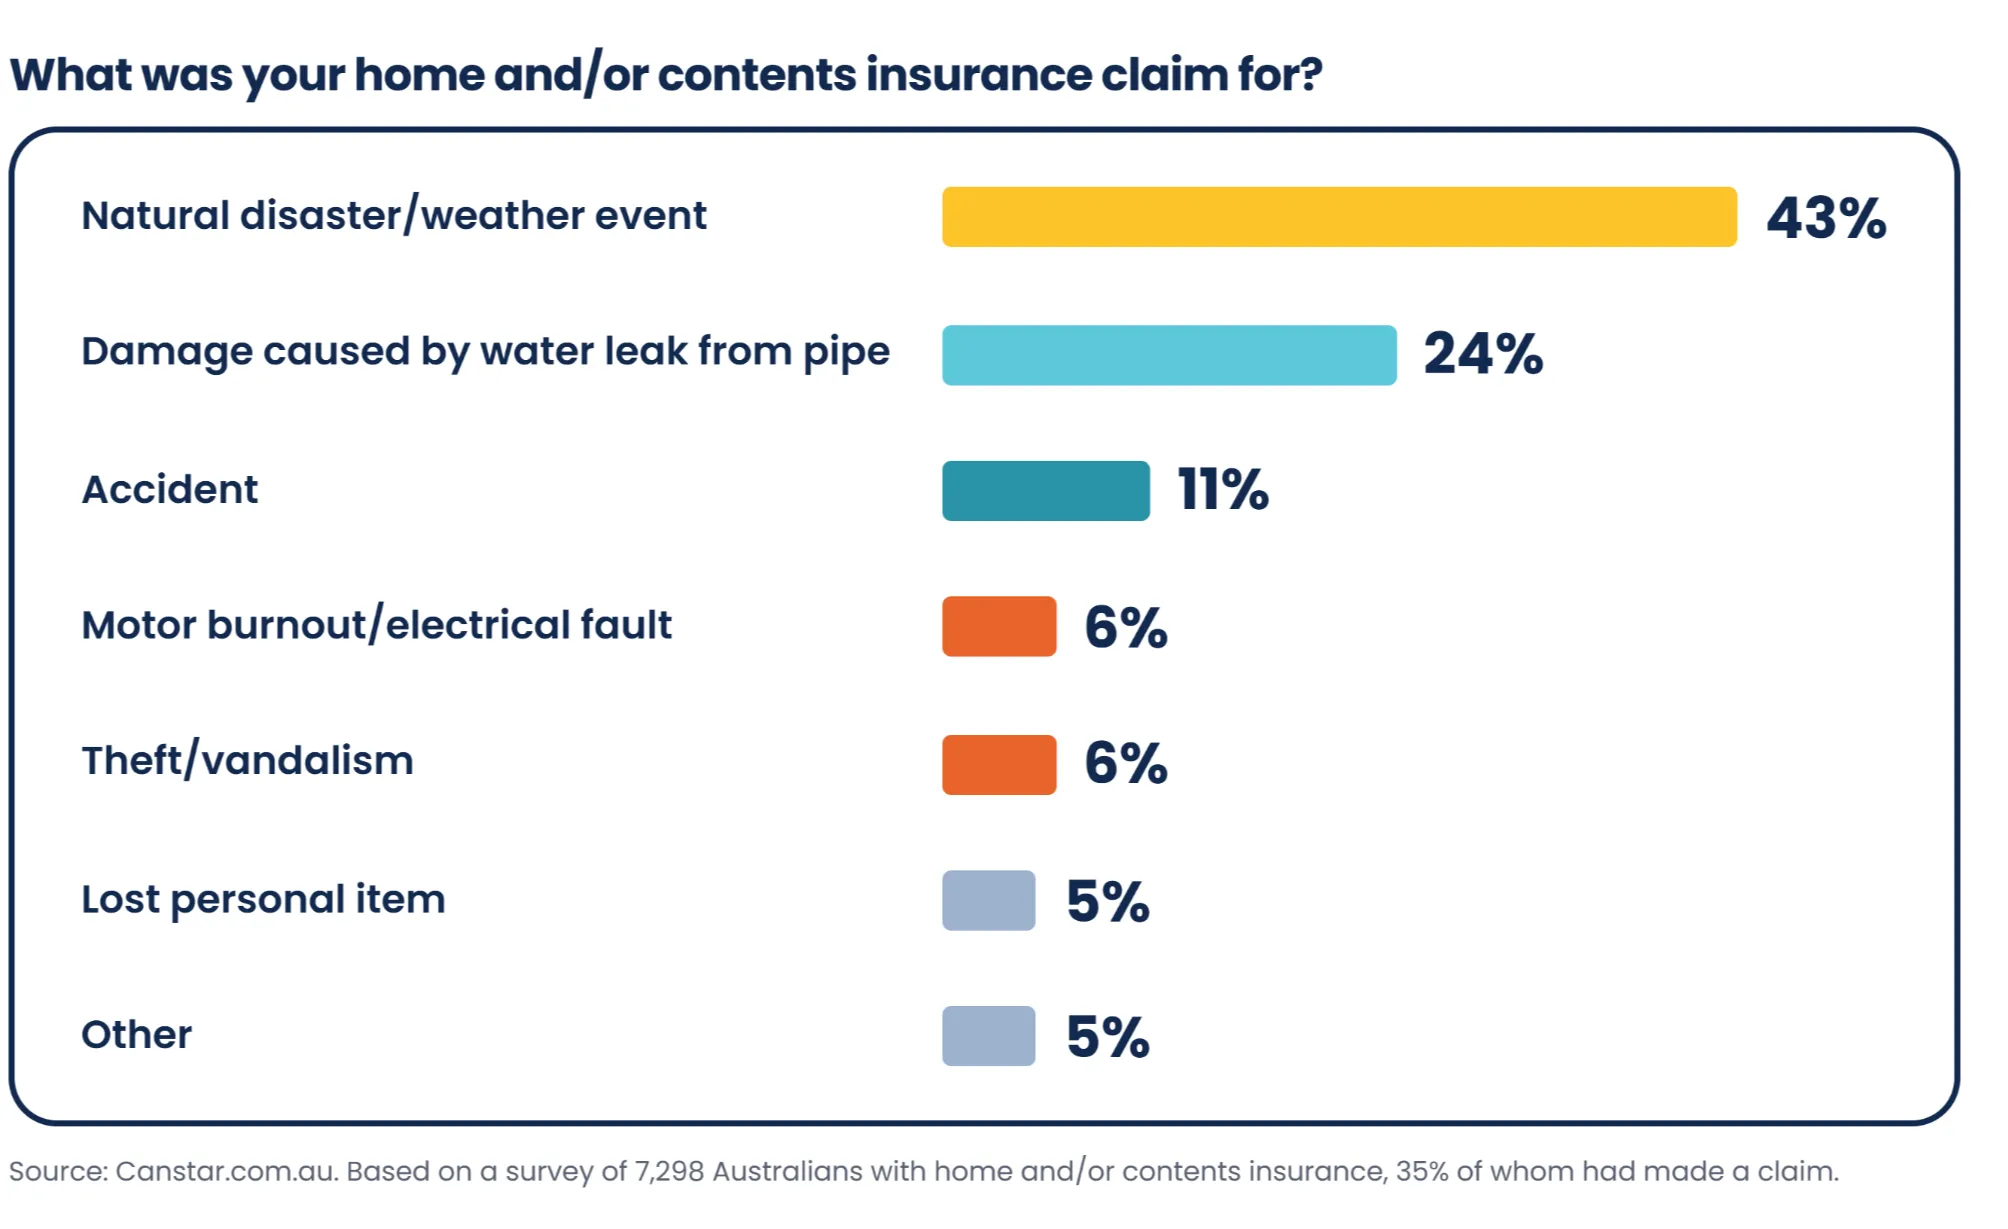
A Canstar survey of 7,298 insured Australians found 35% have made a home insurance claim, with almost half (48%) of those claims occurring since 2021.
Natural disasters or weather events were the most common cause of claims, followed by water leaks from pipes and accidents.
A saving of almost $500 is sitting on the table for those who compare
A typical homeowner who opts for a Canstar award-winning provider’s policy instead of an average-priced one could save an estimated $475 or 20% in a year.
Potential savings range from $298 in South Australia to up to $881 in North Queensland.
Importantly, this research is not the difference between the average and lowest-priced policies, as insurance should not be a race to the cheapest option. Canstar assesses providers not just on price but also on what is included in their cover.
Figures are indicative comparisons, not guaranteed savings for individual households.
Potential savings of switching annual home insurance | |||
|---|---|---|---|
Market average | Award winners | Savings | |
NSW | $2,413 | $1,988 | -$425 (-18%) |
VIC | $2,104 | $1,577 | -$527 (-25%) |
North QLD | $4,295 | $3,414 | -$881 (-21%) |
QLD* | $3,029 | $2,600 | -$429 (-14%) |
SA | $1,763 | $1,465 | -$298 (-17%) |
WA | $2,016 | $1,466 | -$550 (-27%) |
TAS | $1,995 | $1,402 | -$593 (-30%) |
NT | $4,749 | $4,247 | -$502 (-11%) |
National | $2,420 | $1,945 | -$475 (-20%) |
Source: Canstar. Premiums based on policies rated in Canstar's 2026 Home Insurance Awards (August 2026), for a range of addresses, property assumptions and building sum insured amounts.
*QLD excludes the portion of the state north of, but not including, Rockhampton. Award winners' average premium based on both national and state award-winning policies. National average based on state averages weighted by state population per ABS National, state and territory population (March 2026).
Other ways to save on home insurance
- Check if a higher excess makes sense: Opting for a higher excess can reduce your premium, but make sure you can afford to pay it if you need to make a claim.
- Don’t overinsure: Check that your sum-insured amount reflects the cost of rebuilding your home, including labour and materials, rather than its market value.
- Pay annually if you can: Canstar’s database shows 37% of providers charge more for monthly payments.
- Look for discounts: Some providers offer a discount if you purchase online.
Which providers came out on top in Canstar’s annual home insurance awards?
Canstar researched and rated 60 insurance products from 43 insurance providers to determine which brands offered value.
Each policy was assessed equally on price and features, taking into account the cost of cover, excesses, policy limits, settlement options and the customer journey from application through to cancellation.
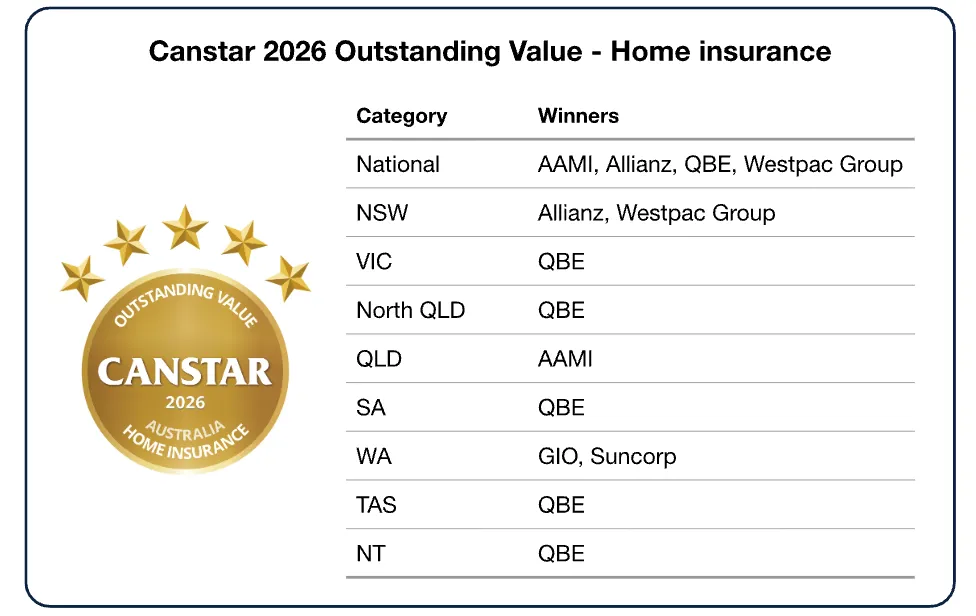
This year’s award-winning home insurance providers include 4 national winners and 6 state winners:
Don’t automatically renew your policy without checking your options
Canstar's Data Insights Director, Sally Tindall, says, “Homeowners are being squeezed by rising insurance costs, with premiums up 4 per cent nationally over the past year.”
“For a typical household, this means their home insurance is now costing them almost $50 a week.
“But the headline figure only tells part of the story, with the impact varying significantly depending on where you live, with home insurance costs up by 8 per cent in the Northern Territory and 6 per cent in Tasmania.
“While rising building costs and weather-related claims are putting upward pressure on premiums, there are still ways homeowners can take control of their costs.
“Canstar’s analysis shows if a typical household opted for a policy from an award-winning home insurer instead of an average one, they could save around $475 a year. That’s almost five times more than this year’s average price hike.
“Don’t automatically roll over your policy at renewal without checking whether you could get a better deal elsewhere, particularly if you are a loyal existing customer.
“Just remember, cheaper isn’t always better. Check the cover, exclusions, limits and excess carefully to make sure you’re getting the protection you need, not just the lowest price.
“If you’re looking for other ways to cut costs, review your excess, check your building sum insured reflects realistic rebuilding costs, and consider paying annually if you can afford to. Some insurers charge more for monthly payments.
“The aim is to find the best-value cover for your home, rather than cutting corners and leaving yourself exposed if you need to make a claim.”