


The RBA’s card surcharge ban (those pesky fees when you go to pay for something with a card) kicks in on 1 October.
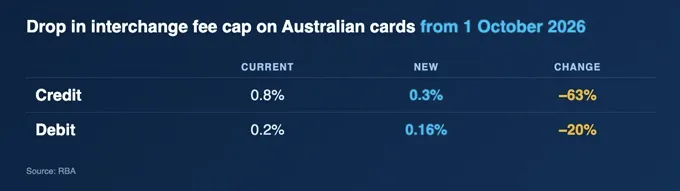
As part of the overhaul, the RBA is cutting the amount banks can charge at the back-end to help facilitate these card transactions, to make it cheaper for stores to accept card payments.
However, because the banks will soon be making less money on these transactions, they’re overhauling their credit card programs to compensate. That could mean fewer points, higher fees, changes to insurance or other perks being added, removed or reshaped.
Find out how your credit card will be impacted below.
Click the following links to jump to your bank or card to see the key changes announced so far:
- American Express
- ANZ
- Bank of Melbourne
- BOQ
- BankSA
- Bankwest
- CBA
- Coles
- David Jones
- Latitude Financial
- MyCard
- NAB
- St. George
- Suncorp
- Westpac
- Virgin Money
American Express
American Express: Effective 4 May to 1 October unless otherwise stated | |
Platinum | Foreign currency conversion fee increased from 3% to 3.5% from 4 May 2026. Changes to complimentary lounge access from two included guests to one, from 8 July 2026. Complimentary Priority Pass access for additional cardholder will end from 1 October. |
ANZ
ANZ: Effective 28 Sept 2026 unless otherwise stated | |
Rewards Black |
|
Rewards Platinum | Interest rate increasing from 20.99% to 22.49%. Rewards points capped after $25,000 monthly spend (from 28 Oct). International and domestic travel insurance, including rental vehicle excess cover, being scrapped (from 9 Dec 2026). |
Frequent Flyer Black | Interest rate increasing from 20.99% to 22.49%. Qantas Points capped after $50,000 monthly spend (from 28 Oct). Overseas travel insurance significantly reduced, including lower benefit limits and shorter maximum cover period (from 24 Mar 2027). |
Frequent Flyer Platinum | Interest rate increasing from 20.99% to 22.49%. Qantas Points capped after $25,000 monthly spend (from 28 Oct). Overseas travel insurance reduced, including lower benefit limits and shorter maximum cover period (from 9 Dec 2026). |
First | Interest rate increasing from 20.99% to 22.49%. |
Platinum | Interest rate increasing from 20.99% to 22.49%. Overseas travel insurance reduced, including lower benefit limits (from 9 Dec). |
Low Rate | Purchase rate unchanged at 13.74%. Cash advance and balance transfer rates increasing. |
Bank of Melbourne
Bank of Melbourne: Effective 30 September unless otherwise stated | |
Amplify Rewards Platinum | Purchase rate increasing from 20.99% to 23.99%. Annual fee increasing from $175 to $250. Burn rate increasing up to 72%. Min payment due will increase from 2% or $10 to 2.5% or $25. Interest free period will reduce from 55 days to 45 days. |
Amplify Rewards Signature | Purchase rate increasing from 20.99% to 23.99%. Annual fee increasing from $295 to $370. Burn rate increasing up to 72%. Min payment due will increase from 2% or $10 to 2.5% or $25. Interest free period will reduce from 55 days to 45 days. |
Amplify Qantas Platinum | Purchase rate increasing from 20.99% to 23.99%. Annual fee increasing from $250 to $300. Earn rate changing to 0.33–0.75 points/$ on the first $5,000 of monthly spend, then 0.20 points/$ depending on where you shop. Min payment due will increase from 2% or $10 to 2.5% or $25. Interest free period will reduce from 55 days to 45 days. |
Amplify Qantas Signature | Purchase rate increasing from 20.99% to 23.99%. Annual fee increasing from $370 to $450. Earn rate changing to 0.4–1.5 points/$ on the first $10,000 of monthly spend, then 0.25 points/$ depending on where you shop. Min payment due will increase from 2% or $10 to 2.5% or $25. Interest free period will reduce from 55 days to 45 days. Changes to lounge invitation eligibility. |
BOQ
BOQ: Effective 1 Oct 2026 unless otherwise stated | |
Platinum | Interest rate increasing from 20.99% to 21.99%. Earn rate changing from 2 points/$ to a tiered rate of 1–3 points/$ depending on spend. |
Blue | Interest rate increasing from 20.99% to 21.99%. |
BankSA
BankSA: Effective 30 September unless otherwise stated | |
Amplify Rewards Platinum | Purchase rate increasing from 20.99% to 23.99%. Annual fee increasing from $175 to $250. Burn rate increasing up to 72%. Min payment due will increase from 2% or $10 to 2.5% or $25. Interest free period will reduce from 55 days to 45 days. |
Amplify Rewards Signature | Purchase rate increasing from 20.99% to 23.99%. Annual fee increasing from $295 to $370. Burn rate increasing up to 72%. Min payment due will increase from 2% or $10 to 2.5% or $25. Interest free period will reduce from 55 days to 45 days. |
Amplify Qantas Platinum | Purchase rate increasing from 20.99% to 23.99%. Annual fee increasing from $250 to $300. Earn rate changing to 0.33–0.75 points/$ on the first $5,000 of monthly spend, then 0.20 points/$ depending on where you shop. Min payment due will increase from 2% or $10 to 2.5% or $25. Interest free period will reduce from 55 days to 45 days. |
Amplify Qantas Signature | Purchase rate increasing from 20.99% to 23.99%. Annual fee increasing from $370 to $450. Earn rate changing to 0.4–1.5 points/$ on the first $10,000 of monthly spend, then 0.25 points/$ depending on where you shop. Min payment due will increase from 2% or $10 to 2.5% or $25. Interest free period will reduce from 55 days to 45 days. Changes to lounge invitation eligibility. |
Bankwest
Bankwest: Effective 1 October unless otherwise stated | |
Zero Platinum | Max credit limit to reduce from $6k to $1k. |
Breeze Platinum | Max credit limit to reduce from $6k to $1k. Complimentary insurance changes including adding overseas funeral cover, baggage delay expenses and removing benefits such as accidental death, extended warranty, purchase protection. |
More World | Earn rate changing to 2.5 points/$1 up to $2k per month then 0.5 points/$1. Max credit limit to reduce from $12k to $6k. Complimentary insurance changes including adding overseas funeral cover, baggage delay expenses and removing benefits such as accidental death, extended warranty, purchase protection. |
Qantas Classic | Earn rate changing to 0.25 Qantas points/$1 up to $1.5k per month then 0.1 points/$1. |
Qantas Platinum | Earn rate changing to 0.6 Qantas points/$1 up to $2.5k per month then 0.15 points/$1. Max credit limit to reduce from $3k to $1k. Complimentary insurance changes including adding overseas funeral cover, baggage delay expenses and removing benefits such as accidental death, extended warranty, purchase protection. |
Qantas World | Earn rate changing to 1 Qantas points/$1 up to $3k per month then 0.2 points/$1. Max credit limit to reduce from $12k to $6k. Complimentary insurance changes including adding overseas funeral cover, baggage delay expenses and removing benefits such as accidental death, extended warranty, purchase protection. |
Zero Classic, Breeze Classic, More Classic, More Platinum | Discontinued for sale |
CBA
CBA: Effective from 29 Sept 2026 - 1 Jan 2027 | |
| |
| |
| |
All eligible Awards points customers |
|
Coles
Coles: Effective 1 October unless otherwise stated | |
Rewards Mastercard | Purchase rate increasing from 20.74% to 21.99%. Earn rate changing to 2 Flybuys points/$1 on eligible purchases at Coles and 1 point/$1 everywhere else up to $8k per statement period. Complimentary purchase protection and extended warranty insurance removed and complimentary mobile phone insurance introduced from 1 Dec 2026. |
No Annual Fee Mastercard | Purchase rate increasing from 20.74% to 21.99%. Complimentary purchase protection and extended warranty insurance removed from 1 Dec 2026. |
Low Rate Mastercard | Complimentary purchase protection and extended warranty insurance removed from 1 Dec 2026. |
David Jones
David Jones (by Latitude Financial) : Effective 25 August 2026 unless otherwise stated | |
Prestige | Annual fee increased from $295 to $345. New fee waiver in year 1 when spending $36,000 on eligible purchases. Max interest free days changed from 55 to 44 days, new payment due dates apply. 5% credit back capped at $350 per year. Earn rates changed to 3 points/$ at David Jones, 1 point/$ everywhere else. Increases to burn rates. |
Premier | Annual fee increased from $99 to $149. New fee waiver for spend of $24,000 on eligible purchases. Max interest free days changed from 55 to 44 days, new payment due dates apply. Earn rates changed to 2points/$ at David Jones, 1 point/$ everywhere else. Increases to burn rates. |
Icon (not available to new customers) | Max interest free days changed from 55 to 44 days, increases to burn rates. |
Latitude Financial
Latitude Financial: Effective 20 May to 15 July 2026 unless otherwise stated | |
GO Mastercard, GO Platinum Mastercard | From 15 July, the monthly fee increased from $10.95 to $11.95. Minimum monthly payment changed from 3% or $25 whichever is greater, to 2.75% or $30. Interest free payment plan changed from 33 months to 37 months. From 20 May, purchase rate increased from 28.49% to 28.99%. |
Gem Visa | From 15 July, the monthly fee increased from $10.95 to $11.95. Minimum monthly payment changed from 3% or $25 whichever is greater, to 2.75% or $30. Interest free payment plan changed from 33 months to 37 months. From 20 May, purchase rate increased from 28.49% to 28.99%. |
Low Rate Mastercard | From 15 July, minimum monthly payment changed from 3% or $25 whichever is greater, to 2.75% or $30. |
28° Global Platinum Mastercard | From 20 May, purchase rate increased from 28.49% to 28.99%. |
Infinity Rewards Visa (not available to new customers) | From 20 May, purchase rate increased from 28.49% to 28.99%. |
Eco Mastercard (not available to new customers) | From 20 May, purchase rate increased from 28.49% to 28.99%. |
Latitude Mastercard (not available to new customers) | From 20 May, purchase rate increased from 28.49% to 28.99%. |
MyCard
MyCard: Effective 1 October unless otherwise stated | |
Premier | Everyday earn rate increasing from 1 to 1.5 points/$. Burn rate increasing by up to 62%. |
Premier Qantas | Earn rate on overseas and online spending falling from 1 to 0.5 points/$. Burn rate increasing by up to 62%. |
Rewards | Earn rate increasing from 1 to up to 2 points/$. Annual fee increasing from $199 to $249. Burn rate increasing by up to 62%. |
Prestige | Card discontinued. |
NAB
NAB: Effective 1 October unless otherwise stated | |
Rewards Platinum | Purchase rate increasing from 20.99% to 22.49%. Points earn rate changing from 1–2 points/$ to 0.5–2 points/$, depending on where and how much you spend. |
Rewards Signature | Purchase rate increasing from 20.99% to 22.49%. Annual fee changing from $35/month to $395/year and fee waiver removed. Earn rates changing, with new grocery and petrol bonus points. Two airport lounge passes added. |
Qantas Rewards Premium | Purchase rate increasing from 20.99% to 22.49%. Qantas Points earn rate falling, including from 0.75 to 0.5 points/$ on the first $3,000 of monthly spend. Bonus 0.5 point/$ on international spending. International travel insurance cover was reduced from 3 mths to 30 days since May 2026. Increase to travel delay cover to include meals & accommo for every 24 hours of delay. |
Qantas Rewards Signature | Purchase rate increasing from 20.99% to 22.49%. Annual fee increasing from $420 to $449 for new customers. Qantas Points earn rates falling, including from 1 to 0.75 points/$ on the first $3,000 of monthly spend. Bonus 0.5 point/$ on international spending. |
St George
St. George: Effective 30 September unless otherwise stated | |
Amplify Rewards Platinum | Purchase rate increasing from 20.99% to 23.99%. Annual fee increasing from $175 to $250. Burn rate increasing up to 72%. Min payment due will increase from 2% or $10 to 2.5% or $25. Interest free period will reduce from 55 days to 45 days. |
Amplify Rewards Signature | Purchase rate increasing from 20.99% to 23.99%. Annual fee increasing from $295 to $370. Burn rate increasing up to 72%. Min payment due will increase from 2% or $10 to 2.5% or $25. Interest free period will reduce from 55 days to 45 days. |
Amplify Qantas Platinum | Purchase rate increasing from 20.99% to 23.99%. Annual fee increasing from $250 to $300. Earn rate changing to 0.33–0.75 points/$ on the first $5,000 of monthly spend, then 0.20 points/$ depending on where you shop. Min payment due will increase from 2% or $10 to 2.5% or $25. Interest free period will reduce from 55 days to 45 days. |
Amplify Qantas Signature | Purchase rate increasing from 20.99% to 23.99%. Annual fee increasing from $370 to $450. Earn rate changing to 0.4–1.5 points/$ on the first $10,000 of monthly spend, then 0.25 points/$ depending on where you shop. Min payment due will increase from 2% or $10 to 2.5% or $25. Interest free period will reduce from 55 days to 45 days. Changes to lounge invitation eligibility. |
Suncorp
Suncorp: Effective 1 December unless otherwise stated | |
Feel Good Rewards | To be discontinued. |
Westpac
Westpac: Effective 30 September unless otherwise stated | |
Altitude Rewards Platinum | Purchase rate increasing from 20.99% to 23.99%. Annual fee increasing from $175 to $250. |
Altitude Rewards Black | Purchase rate increasing from 20.99% to 23.99%. Annual fee increasing from $295 to $370. |
Altitude Qantas Platinum | Purchase rate increasing from 20.99% to 23.99%. Annual fee increasing from $250 to $300. Earn rate changing to 0.33–0.75 points/$ on the first $5,000 of monthly spend, then 0.20 points/$ depending on where you shop. |
Altitude Qantas Black | Purchase rate increasing from 20.99% to 23.99%. Annual fee increasing from $370 to $450. Earn rate changing to 0.4–1.5 points/$ on the first $10,000 of monthly spend, then 0.25 points/$ depending on where you shop. |
Altitude Velocity Platinum | Purchase rate increasing from 20.99% to 23.99%. Annual fee increasing from $250 to $300. Earn rate changing to 0.33–0.75 points/$ on the first $5,000 of monthly spend, then 0.20 points/$ depending on where you shop. |
Altitude Velocity Black | Purchase rate increasing from 20.99% to 23.99%. Annual fee increasing from $370 to $450. Earn rate changing to 0.4–1.5 points/$ on the first $10,000 of monthly spend, then 0.25 points/$ depending on where you shop. |
Virgin Money
Virgin Money: Effective 1 October unless otherwise stated | |
Anytime Rewards | Annual fee increasing from $149 to $169. Interest rate increasing from 19.99% to 21.99%. Earn rate falling from 1 point/$ to a tiered rate of 0.5–1 point/$. |
Velocity Flyer | Annual fee increasing from $149 to $169. Interest rate increasing from 20.74% to 21.99%. Maximum earn rate falling from 0.66 to 0.5 points/$. |
Velocity High Flyer | Annual fee increasing from $329 to $349. Interest rate increasing from 20.74% to 21.99%. Maximum earn rate falling from 1 to 0.75 points/$. |
These tables highlight the main announced changes and is not a complete list of every change to every card. Check your provider's latest notice and the terms and conditions for your specific card.
Why are banks changing rewards cards?
The RBA will move to scrap surcharges on both credit and debit cards across the Visa, Mastercard and eftpos network from 1 October. These are the small fees you pay whenever you tap to purchase at the point of sale.
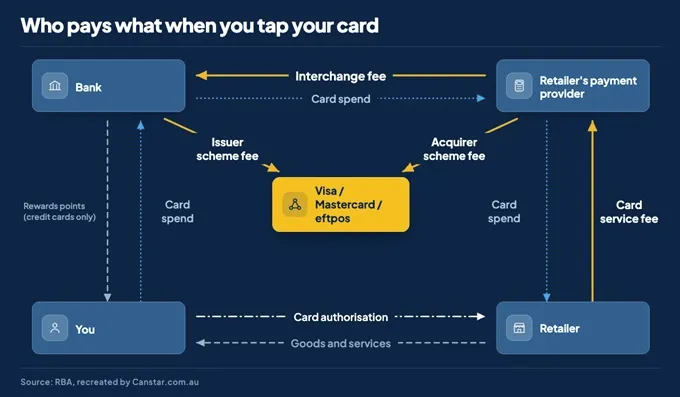
The upcoming ban on credit and debit card surcharges on 1 October, which was initiated by the RBA, includes a reduction in interchange fees – a fee charged at the backend to help facilitate card payments.
The central bank is doing this to reduce the cost of receiving card payments for small businesses who will no longer be able to directly pass this cost on to shoppers.
However, these fees help fund credit card rewards programs, which means there will be significantly less money available for the rewards, perks and complimentary insurances many credit card users have grown accustomed to.
What does this mean for me?
If you have a rewards credit card, there are three things to check.
1. Are you earning fewer points?
Check whether your points or frequent flyer earn rate is changing.
A change from 1 point per $1 to 0.5 points per $1 might sound small, but it can make a big difference over a year if you put a lot of spending through your card.
Also check whether:
- bonus points are being removed or added;
- points now depend on how much you spend;
- certain retailers or spending categories earn fewer points;
- there are new monthly or annual points caps; or
- the number of points needed to redeem a reward is changing.
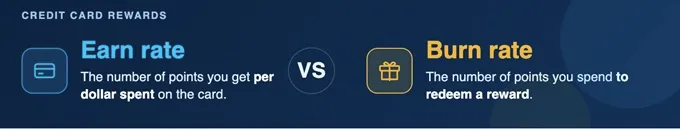
Don't just check the earn rate, check the burn rate too.
The earn rate is how quickly you collect points when you spend. For example, if your card earns 1 point per $1 spent, your earn rate is 1 point per dollar.
Burn rate is how many points you need to spend to get a reward. This is important because a card can keep its earn rate unchanged while quietly becoming less valuable if the number of points needed to redeem rewards increases.
For example, CBA is changing select burn rates on its rewards program, including to redeem gift cards via Myer.
Example of changes to the number of points required to redeem rewards: CBA | |||
| Pts required before 29 Sept | Pts required after 29 Sept | Change |
$50 Myer Gift Card | 10,950 | 12,500 | +14% |
Source: CBA. Note: Points amounts are estimates.
While Westpac is also increasing the burn rates on its rewards program, effectively reducing the value of points when redeeming certain options.
Examples of changes to the number of points required to redeem rewards: Westpac | |||
| Pts required before 30 Sept | Pts required after 30 Sept | Change |
$100 eGift Card | 23,500 | 29,412 | +25% |
$100 cashback | 28,200 | 31,250 | +11% |
$100 annual fee rebate | 20,000 | 26,316 | +32% |
Source: Westpac. Note: Points amounts are estimates.
2. Are you losing valuable perks?
Rewards cards often come with extras such as:
- complimentary travel insurance;
- airport lounge access;
- purchase protection;
- extended warranties;
- travel credits;
- concierge services; or
- other lifestyle benefits.
A card can still offer the same number of points while becoming less valuable because other benefits have been removed or reduced.
If you rely on your card’s travel insurance, read the new policy carefully before your next overseas trip.
3. Is your card getting more expensive?
Check for changes to:
- annual fees;
- monthly fees;
- interest rates;
- foreign transaction fees; and
- other card charges.
A rewards card isn’t necessarily good value simply because it earns points.
If you’re paying hundreds of dollars a year for a card, you need to make sure the value of the rewards and perks you actually use outweighs those costs.
What should I do if my card is changing?
Don’t panic, but don’t ignore the email either.
Your provider should notify you if the terms of your card are changing. Look out for emails, letters or messages in your banking app.
When you receive one, do this five-minute health check:
Step 1: Write down what you currently get
Check your:
- annual fee;
- interest rate;
- points earn rate;
- frequent flyer points;
- insurance;
- lounge access; and
- other perks you actually use.
Step 2: Compare it with the new offer
Ask yourself:
- Am I earning fewer points?
- Am I paying more?
- Have any perks I actually use disappeared?
- Are the new benefits genuinely useful to me?
Step 3: Check your points balance
If your provider is changing its rewards program, check whether you need to do anything with your existing points.
Don’t automatically rush to redeem your points, but make sure you understand whether the value or redemption rules are changing.
Step 4: Work out what your card is really worth
Think about how much you spend on the card each year and the rewards you realistically receive.
For example, there’s little value in paying a premium annual fee for airport lounge access if you never fly.
Likewise, a card with a lower points earn rate may still be worthwhile if you use its other benefits regularly.
Step 5: Compare your options
If the numbers no longer stack up, consider whether another card offers better value or whether you need a rewards card at all.
Remember: if you carry a balance from month to month, the interest charged can quickly outweigh the value of any rewards you earn.
