
What is a land loan?
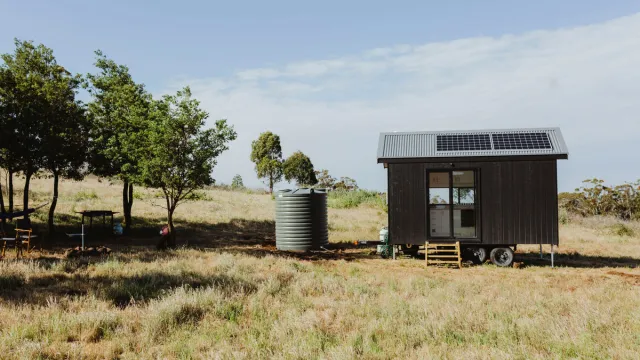
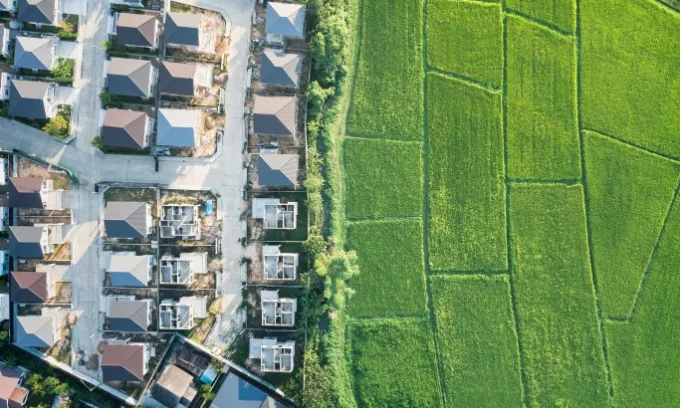
A land loan is a home loan you can use to buy vacant land. Many borrowers also take out a construction loan to build a new property atop the land they’ve bought, although some lenders may also allow buying before you’ve decided to build or in the hopes the value of that plot will rise. As with a normal home loan, what you’re buying (the plot of land) is security for the loan.
What are the eligibility requirements for a land loan?
The eligibility requirements for land loans are broadly similar to other kinds of home loans. You'll need to show a lender proof of your identity and income, and be able to show capacity to repay the loan.
Lenders sometimes are more conservative when handing out money for land loans, which are often perceived as riskier than normal home loans. That’s because land prices can fluctuate significantly and vacant lots can take longer to sell—annoying for lenders if they need to repossess and sell it to recover their losses.
For this reason, land loans sometimes have stricter lending conditions, like larger deposit requirements and higher interest rates.
How do land loans work?
Just like any home loan, if you apply for a land loan your lender will assess your borrowing power, income, assets, and debts. Lenders often allow interest-only periods on land loans, which could be useful if you’re saving to build.
Your lender will also consider the plot of land, getting a valuation and assessing whether it’s suitable for a land loan. If you’re buying a patch of dirt deep in the outback, inaccessible by road, for example, you might have trouble getting finance. Factors lenders may look at can include:
- Size of the block
Lenders may ask for a bigger deposit on larger blocks. - Its location, and how easily accessible it is.
- Zoning restrictions that could affect a potential build
- Whether the land is registered or unregistered
Lenders usually don’t like applications for unregistered land. - The availability of infrastructure like roads and utilities
- Environmental factors
For instance, whether the land is in a flood plain.
Your intentions can also be important. Some lenders only allow land loans if you plan to build on it within a certain time period. Even lenders that are more flexible might still be more reluctant to lend to you if you don’t have any intention to build, seeing you as higher risk.
Do land loans require a bigger deposit?
The deposit you’ll need for a land loan can vary based on the value of the block of land and which lender you choose. Lenders often have a lower max loan to value ratio (LVR) they’re willing to accept for land loans, which might mean you need a deposit as high as 20% or 30%.
Do you have to build if you take out a land loan?
Some lenders might require you to start building atop the land you’re buying within a certain period. This usually isn’t immediate though, so you may have some leeway if you aren’t ready to get building right away.
How do land loans and construction loans differ?
Many borrowers combine land loans with construction loans if they plan to build right away. Construction loans are structured differently to conventional home loans, often interest-only for the construction period and only paying interest on funds you gradually ‘draw down’ as you build.
A standalone vacant land loan might be more suitable if you aren’t planning to build right away.
Pros and cons of buying land using a land loan
There can be several benefits to buying vacant land rather than an established property:
- You can design your own property
- You might be able to subdivide and end up owning multiple properties
- In some states you may pay a concessional rate of stamp duty for buying vacant land.
- You may be able to access the 5% Deposit Scheme to buy land if you’re a first home buyer.
However, there are also plenty of potential risks:
- Land values can be more volatile than those of established properties.
- Your lender’s valuation may be significantly lower than what you actually pay, which might mean you need to pay more up front.
- Vacant land can also be harder to sell.
- If you build, construction could get significantly delayed, or the costs could majorly escalate (or both).
What lenders offer land loans in Australia?
Many lenders in Australia, including the major banks, offer land loans. If you’re in the market, these are some of the most important things to keep in mind when comparing your options:
- Interest rates. Rates can be higher on land loans compared to normal home loans, which means finding a lower rate can be even more important.
- Lending restrictions. Many lenders require a larger deposit for land loans, while the maximum loan amount may be lower.
- Your plans. Some lenders will only give you a land loan if you pledge to build on the land within a certain time frame.
- Construction loan combination. Some lenders may have more relaxed lending conditions and potentially lower rates if you combine your land loan with a construction loan.