




What is the difference between comprehensive and third party insurance?
The main differences between comprehensive and third party insurance policies lie in their level of protection and the cost of their premiums.
Third party insurance
Third party property damage insurance
Third party property damage (TPPD) insurance financially covers you for damage to other people’s property (including their cars) and any associated legal costs.
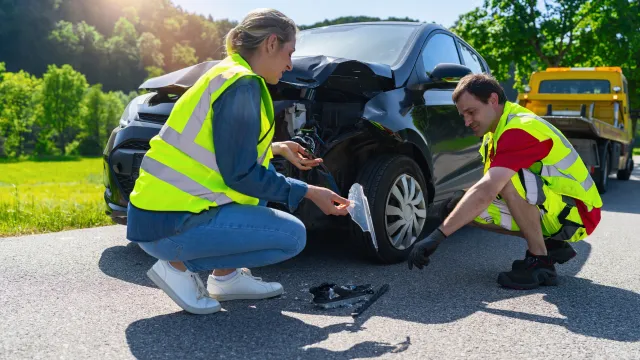
It does not normally insure you if your car is damaged in an accident where you’re at fault. Some providers may cover damage to your vehicle if the other driver is:
- At fault
- Uninsured
- Identifiable by you.
However, the level of cover for your own vehicle can be quite low, usually between $3,000 to $5,000.
Third party fire and theft insurance
Third party fire and theft (TPFT) insurance provides the protection of TPPD insurance, plus cover (up to a set limit) if your car is stolen or damaged by attempted theft or fire.
The level of cover will depend on your car insurance provider.
That said, it can be limited, with some providers only covering up to $10,000. This may not be enough to pay for the repairs or replacement of your car, so you could potentially be out of pocket if you need to make a claim.
Comprehensive car insurance
Comprehensive car insurance provides the highest level of financial protection for you and your car. It can
- Protect you for the repair or replacement of your car following theft, a collision, fire, malicious and weather-related damage.
- Cover the cost of repairs or replacement of any other vehicles damaged by you in a collision, as well as damage to other people's property.
Some comprehensive policies also offer extras such as roadside assistance, either as part of the standard policy or available as an add-on at an extra cost.
Unlike third party insurance, on some comprehensive policies you may have the option to choose how much your car is insured for: either market value or an agreed value. In comparison, third party policies may only cover you for your car’s market value.
Is it better to have comprehensive or third party insurance?
There is no one-size-fits-all answer to whether third party insurance is better than comprehensive cover. It all comes down to which is the best option for you. Let’s look at some of the factors to consider when choosing a level of cover.
Cost vs cover
Third party car insurance provides less protection, so it generally comes with lower premiums. Bear in mind that this lower level of protection usually won’t cover your car if it’s damaged in an accident or a weather event.
If you take out third party fire and theft cover, you will be covered for damage to your car from fire or theft, with limits applying.
Comprehensive car insurance offers the widest level of coverage, including damage caused to your own vehicle if you’re either at fault or not at fault, although certain conditions apply.
If your vehicle is worth more than what you are covered for, you could be underinsured if you need to make a claim. On the flipside, if your car is worth less than your level of cover, you may be paying too much to overinsure it.
Are you required to have comprehensive cover?
If you took out a car loan or other type of finance to buy the vehicle, your lender may make it a condition that you have comprehensive car insurance in place. This protects you and the lender if your car has to be written off. Your insurance may be able to cover the cost of replacement and/or pay off the remaining loan.
Ways to save on car insurance
It may be possible to save money on your car insurance by taking simple steps like:
- Parking your car in a safe location, such as a secure garage or carport.
- Investing in security devices like an immobiliser to deter would-be burglars.
- Avoid modifying your car.
- Maintaining a safe driving record. If you haven’t submitted a claim for a period of time (e.g. a year), you may be entitled to a no claims discount.
- Avoid adding at-risk or younger drivers (especially those aged under-25) to your policy.
- Pay yearly instead of monthly. Some lenders may reduce your premiums if you pay upfront for a year’s worth of cover.
While there are a handful of other ways to reduce your insurance premiums, they come with potential downsides:
- Selecting a higher excess — the price you agree to pay to submit a claim. However, you may be left paying out of pocket if you have to make a claim.
- Avoiding extras you don’t need.
- Looking for car insurance deals and offers each month. Keep in mind that a deal or discount may not save you the most money.
- If you’re considering comprehensive cover, opting for insuring your car for its market value instead of agreed value can help slash your premiums. But this can impact your car’s insured value.
No matter whether you choose comprehensive or third party insurance, the golden rule is to shop around and compare car insurance providers. It’s not just about the potential savings: policy features and benefits vary widely between providers. You need to be sure you have the right protection for your needs.




