


The RBA’s sixth Monetary Policy Board meeting for 2026 has started and is expected to finish with a hike to the official cash rate to 4.60%.
This move would take the cash rate above the 2022-2023 hikes to the highest setting this country has seen since October 2011.
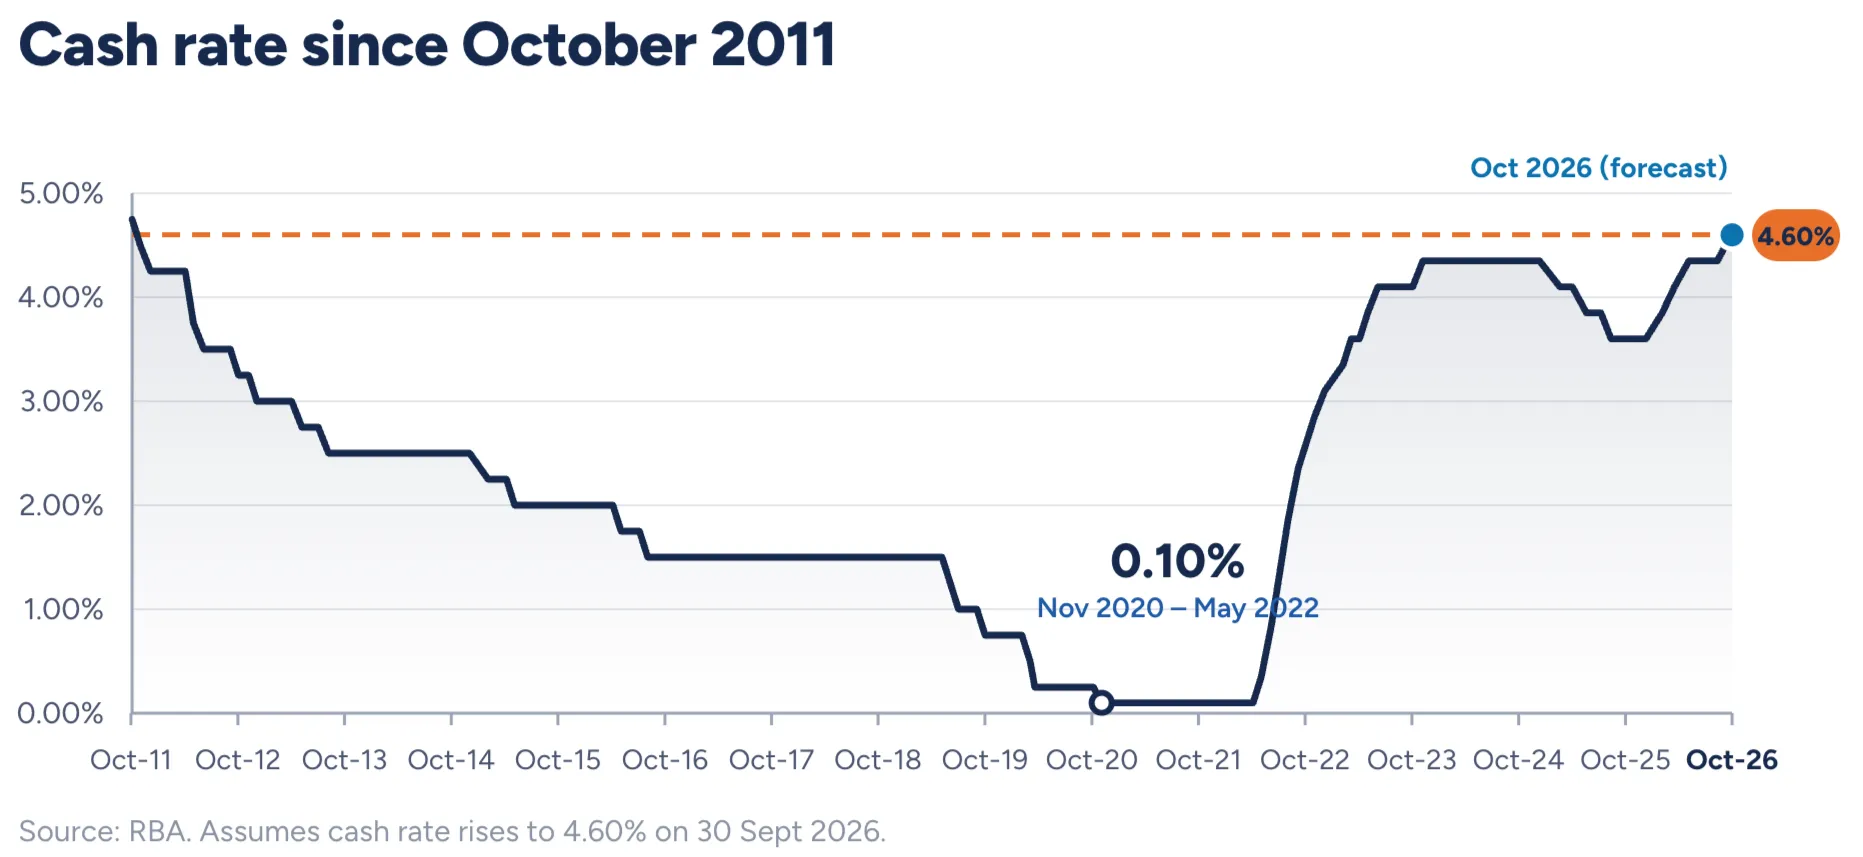
While the cash rate might rise to a 15-year high, home loan debt has risen by 138% in this time primarily due to soaring property prices.
APRA monthly banking statistics shows the total value of residential mortgages was $1.05 trillion in 2011 and $2.51 trillion in the latest data from July 2026.
October 2011 vs today: cash rate, mortgages and house prices | ||
|---|---|---|
Loan size at start of hikes | Oct 2011 | Today |
Cash rate | 4.75% | 4.60% |
Residential mortgages | $1.05 trillion | $2.51 trillion |
Sources: RBA, APRA monthly banking statistics, Cotality.
Borrowers could have to find $364 more a month on a $600k debt
A 0.25 increase would add $91 to the monthly repayments for a borrower with a $600,000 loan and 25 years remaining at the start of this year’s hikes.
However, across what would be four hikes for the year, that’s an increase of $364 to their monthly repayments and over half a thousand dollars extra a month for anyone with $825k debt or more (assumes 25 years remaining).
Note: The impact of an additional hike in November is further below.
Impact of 0.25 cash rate hike in Sept on monthly repayments | ||
|---|---|---|
Loan size at start of hikes | Hike in Sept | Cumulative increase across 4 hikes |
$500,000 | +$76 | +$303 |
$600,000 | +$91 | +$364 |
$700,000 | +$107 | +$424 |
$800,000 | +$122 | +$485 |
$900,000 | +$137 | +$545 |
$1 million | +$152 | +$606 |
Source: Canstar. Based on an owner-occupier paying principal & interest with 25 years remaining in Feb 2026 at the avg variable rate. Assumes hike in Sep and banks pass it on the month after. Changes are to min repayments.
What will a decent rate look like after a hike?
If the RBA hikes by 0.25 percentage points, and banks pass it on in full, as they are expected to do, it will push the average owner-occupier variable rate to 6.49%.
However, Canstar expects at least a handful of lenders will hang on to a rate under 6%, with the lowest likely to be 5.94%.
Estimated variable rates if the cash rate rises to 4.60% | ||
|---|---|---|
Owner-occupier | Investor | |
Average | 6.49% | 6.73% |
Competitive | < 6.25% | < 6.45% |
Lowest | 5.94% | 6.19% |
Source: Canstar. Rates are based on Canstar and RBA data.
What should borrowers do?
Do the numbers: Check what your repayments would look like if the RBA hikes, but also if there is a further hike in November.
- Ask for a better rate: Call your bank and ask for a rate review.
- Consider refinancing: The sharpest rates are typically reserved for borrowers who move to a new lender. There are switch fees but if you have a sizable debt, it’s likely to pay off relatively quickly.
How much can refinancing actually save borrowers?
Canstar research shows an owner-occupier who took out a new mortgage five years ago and hasn’t renegotiated their loan since, will land on a variable rate of 7.18% after this hike gets passed on.
By switching to a highly competitive rate of 6.24%, this borrower, assuming they have $600,000 remaining on their loan, could potentially save over $10,000 in the next two years, even when factoring in $1,150 in switch costs.
Potential impact of refinancing: $600k debt | |||
|---|---|---|---|
| Rate | Monthly repayments | Cost - next 2 years |
Do nothing | 7.18% | $4,310 | $84,231 |
Refinance | 6.24% | $3,954 | $73,552 |
Difference | -0.94% | -$356 | -$10,121 |
Source: Canstar. Notes: Calculations are estimates based on an owner-occupier who took out an av variable rate mortgage 5 yrs ago and has not negotiated since. Borrower now has $600k debt and 25 yrs to go. Includes $1,150 in switch costs but not ongoing fees or extra repayments. Assumes rates change inline with CBA’s cash rate forecast.
The true pain is in the cumulative impact
Canstar's Data Insights Director, Sally Tindall, says, “A 4.60 per cent cash rate takes us back to 2011 levels, yet we’re collectively stepping onto the field with more than double the debt we were lugging around 15 years ago.
“APRA’s monthly banking statistics shows since 2011 the total value of residential mortgages has risen 138 per cent to $2.51 trillion, with surging property prices the main reason for this.
“A 0.25 percentage point increase tomorrow will add $91 a month to a typical $600,000 mortgage. That’s assuming the banks pass it on, which, if history is anything to go by, is exactly what they’ll do in about 10 to 14 days after a cash rate decision.
“The true pain is in the cumulative impact. Across what is likely to be at least four rate rises for the year, this borrower has to fork out an extra $364 a month compared to what they were paying at the start of the year.
“Owner-occupiers who have let their loan sit on autopilot for years are likely to be on a rate that’s over 7 per cent after this next rate hike.
“However there is an antidote. By actively negotiating or switching to a competitive rate, which we estimate after another hike will be below 6.25 per cent for owner-occupiers, a borrower with a decent sized debt could potentially pocket thousands of dollars in savings in the next couple of years, even when factoring in switch costs.”
Impact of 0.25 cash rate hike in Sep + Nov on monthly repayments | ||||
|---|---|---|---|---|
Loan size at start of hikes | Hike in Sep | Cumulative increase across 4 hikes | Hike in Nov | Cumulative increase across 5 hikes |
$500,000 | +$76 | +$303 | +$77 | +$380 |
$600,000 | +$91 | +$364 | +$92 | +$456 |
$700,000 | +$107 | +$424 | +$107 | +$532 |
$800,000 | +$122 | +$485 | +$123 | +$607 |
$900,000 | +$137 | +$545 | +$138 | +$683 |
$1 million | +$152 | +$606 | +$153 | +$759 |
Source: Canstar. Based on an owner-occupier paying principal & interest with 25 years remaining in Feb 2026 at the RBA avg variable rate. Assumes rate hike in Sep and Nov and banks pass it on the month after. Changes are to minimum repayments.
