

What is a classic car?
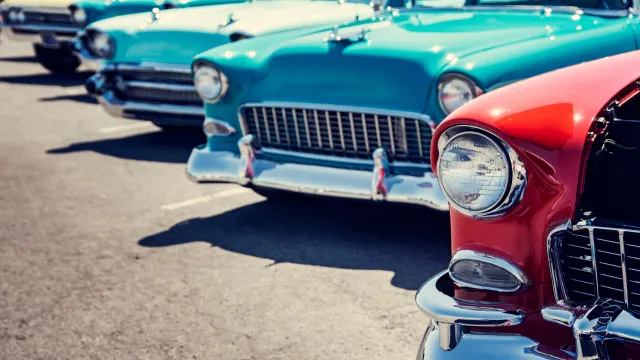
A classic car (not to be confused with modified vehicles) typically refers to an older or collectible car sought after by car enthusiasts. These aren’t your everyday vehicles, but ones you store in a garage and only drive on occasion. Generally, a car is classified as a classic if it's 25 to 30 years old, but there is no binding definition.
However, some modern cars are now considered classic due to their rarity, design, cultural significance and performance capabilities. The Audi R8 is one example of this.
What is classic car insurance?
Classic car insurance is insurance tailored to vintage and classic cars. It generally offers more specialised coverage that comes with options more suitable for collectors and enthusiasts than daily drivers.
Does standard car insurance cover classic cars?
Standard car insurance may cover classic cars, but some insurers restrict cover for older or modified vehicles, or only offer to cover them for market value.
Here’s what you can expect in general from the common types of car insurance:
Damage to | Damage or loss | Damage or loss | |
|---|---|---|---|
Comprehensive | ✔ | ✔ | ✔ |
Third Party | ✔ | ✔ | X |
Third party | ✔ | X | X |
Because policies differ by type and between insurers, it is important to read your policy’s Product Disclosure Statement (PDS) to understand what is covered and not covered.
Why choose classic car insurance over standard car insurance
Market value vs agreed value
When lodging a claim, standard car insurance relies on the market to assess your classic car’s worth up to the time of the covered accident/incident. This is known as ‘market value’.
Your insurer will pull its historic depreciation and recent sales data from vehicle pricing guides like RedBook.
However, market value calculations typically undervalue classic cars significantly. That’s because market value calculations are generically configured for modern cars, not taking into account:
- Restoration costs: Unlike modern cars, the cost spent on restoring or sourcing and replacing rare parts on a classic car is far higher.
- Maintenance costs: Classic cars are also more prone to damage (e.g. rust) and require frequent tuning and oil changes, costing more over time.
- Appreciation: Instead of depreciating, classic cars often appreciate and hold onto their worth because of their collectable nature.
As a result, a market value payout could be well below the car’s actual worth.
Classic car insurance, instead, insures your classic car based on its agreed value — a fixed value you and your insurer set when taking out the policy.
The agreed value stays the same for the policy period, which gives you more certainty about your payout if the car is written off.
Do note that classic car insurance premiums generally cost more than a standard car insurance policy.
Limited use options and laid-up cover
Many classic car insurance policies offer laid-up and limited use cover, which reduces your premiums when these conditions are met:
- Laid-up cover: If your car remains off the road while being restored.
- Limited use cover: If you only drive your car on the weekends or for special occasions.
Choice of repairer
Most classic car insurance policies let you choose which repairer or mechanic fixes your car. This can be helpful, as many classic and vintage car owners already know trusted and experienced repairers.
For standard car insurance, this is generally only offered in comprehensive policies and may be an inclusion or an optional extra.
Salvage rights
Classic car insurance policies usually give you salvage rights, allowing you to keep your classic car’s wreckage if it is written off as a ‘total loss’ (deemed unsafe or too expensive to repair) by your insurer.
The benefit is twofold:
- If your policy includes salvage rights, you may still receive the full agreed value.
- You can salvage rare or hard-to-find parts from your wreckage.
However, it’s worth checking your policy’s PDS to see if any vehicle age restrictions apply.
Some comprehensive car insurance policies may also offer salvage rights, but it's less common.
How much does classic car insurance cost?
Registering your car under a state or territory historic or club scheme could reduce registration and CTP costs, but the age threshold for cars varies between states.
Classic and vintage car insurance policies often vary in price between providers. The factors influencing your premiums include but are not limited to:
- Your car’s agreed value.
- How regularly you drive your classic or vintage car (the more kilometres travelled, the more expensive it is).
- Where your classic or vintage car is stored at night.
- Your car’s make, model, its age and total kilometres done (obtained from an odometer reading).
- Your personal insurance claim history.
- The state and suburb where you live.
- How long you’ve held your licence.
How much is your classic car worth?
For insurance purposes, your classic car is worth the agreed value you and your classic car insurer settle on. Specialist insurers can help appraise your classic car’s real value, relying on auction and classifieds data, its restoration history and the rarity of its parts.
It’s important to keep up-to-date records and photos (e.g. recent restorations, component reconditioning, and/or new parts, trim or tyres) of your classic car to help you when negotiating an agreed value with your insurer.
However, classic car values often go up with time. You can also revise your classic car’s agreed value, but this is usually restricted to when your policy is up for renewal.